“How much is this apartment a month?” — the mortgage calculator on two worked examples
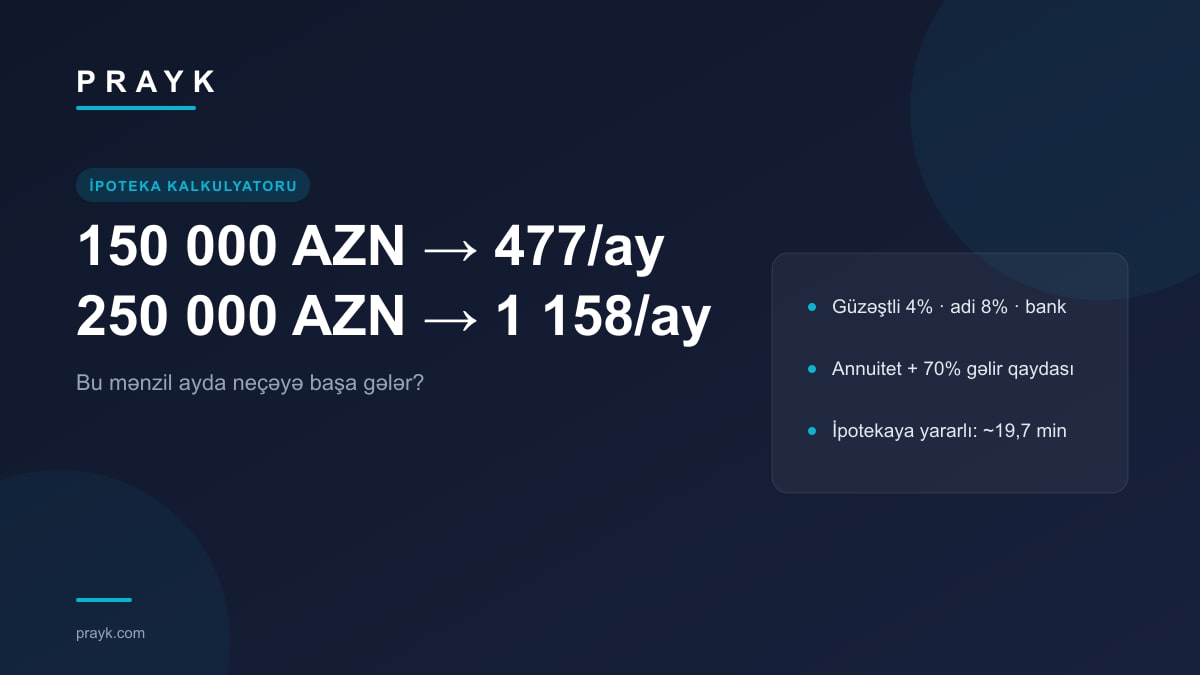
The mortgage calculator shows the monthly payment, the total interest and the minimum income that payment requires as soon as you enter the property price, the down payment and the term — for a preferential mortgage (AMCGF), a standard mortgage (AMCGF) and a commercial bank loan. In this article we run two apartments (150,000 and 250,000 manats) through the page's own formula, show the effect of the down payment and the term, and give the number of mortgage-eligible listings as of 6 October 2026. It is for people planning to buy and for anyone who wants to understand the mortgage line on a listing page.
What the calculator does and does not do
The form has four inputs: loan type, property price, down payment (in manats or with the 10/15/20/30% buttons) and term (1–30 years). The rate is fixed for the AMCGF programmes; for the bank option you type it yourself — 14% is only an example. The calculator's built-in terms (from the official terms on mcgf.gov.az, September 2026): preferential — 4%, loan at most 100,000 ₼, down payment at least 10%, up to 30 years; standard — 8%, at most 150,000 ₼, at least 15% down, up to 25 years. If the terms change, the official source has the final word.
The calculation is an annuity — the same amount every month: A = P·r ÷ (1 − (1 + r)^−n), P — the loan, r — the monthly rate, n — the number of months. The result shows the monthly payment, the loan amount, the total interest, the total cost of the property (with the down payment) and the minimum monthly income (payment ÷ 0.7 — the “payment may not exceed 70% of income” rule). There is no “Calculate” button: the calculation runs in your browser and the figures update as you type.
Not included: insurance, valuation, notary and bank fees; programme eligibility (age, status) is not checked. Prayk does not lend money; the result is for information only and is not financial advice.
Two examples: 150,000 and 250,000 manats
Example 1 — 150,000 ₼, preferential mortgage (the default choice), 20% down = 30,000 ₼, 30 years. The calculator shows 572.90 ₼/month and warns: this programme lends at most 100,000 ₼ — raise the down payment to at least 50,000 ₼. With 50,000 down the loan becomes 100,000 ₼: over 30 years 477.42 ₼/month, total interest 71,870 ₼, the apartment costs 221,870 ₼ in all, minimum income 682 ₼. Over 20 years — 605.98 ₼/month, interest 45,435 ₼, minimum income 866 ₼.
Example 2 — 250,000 ₼. Fitting the preferential limit would take a 150,000 ₼ down payment (more than half the price), so we pick “Standard mortgage”: 20% down = 50,000 ₼, loan 200,000 ₼ — another warning: the limit is 150,000 ₼, raise the down payment to at least 100,000 ₼. With 100,000 down over 25 years: 1,157.72 ₼/month, total interest 197,317 ₼, 447,317 ₼ in all, minimum income 1,654 ₼.
The same apartment through “Commercial bank” (50,000 down, the example 14%, 20 years): 2,487.04 ₼/month, interest 396,890 ₼; type 10 into the rate field and it becomes 1,930.04 ₼/month. In the bank option the rate moves the result more than anything else — enter the rate your bank actually offers you.
What changes with the down payment and the term
The “Compare by term” table shows the same loan over 10–30 years side by side. A 100,000 ₼ loan at 4%:
- 10 years — 1,012.45 ₼/month, interest 21,494 ₼;
- 15 years — 739.69 ₼/month, 33,144 ₼;
- 20 years — 605.98 ₼/month, 45,435 ₼;
- 25 years — 527.84 ₼/month, 58,351 ₼;
- 30 years — 477.42 ₼/month, 71,870 ₼.
When the term doubles (from 15 to 30 years) the monthly payment falls by 35% while the total interest grows 2.2 times. The down payment works linearly: at 4% over 30 years every extra 10,000 ₼ cuts the monthly payment by 47.74 ₼, in the standard programme (8%, 25 years) by 77.18 ₼.
One tap from a listing page, and the October snapshot
In the real-estate section, on the page of a sale listing marked “with title deed” or “mortgage-eligible”, a line “With a mortgage ~X ₼/month · programme · down payment from Y ₼” appears under the price. The figure uses the most accessible AMCGF option: preferential if the price fits the limit (30 years), otherwise standard (25 years), with any excess over the limit added to the down payment; if the down payment would exceed half the price, the line is not shown. “Calculate” opens the calculator with that price filled in. Listings without documents deliberately have no such line (we covered the risks of an apartment without a registry extract).
Snapshot of 6 October 2026: the section holds about 75,000 sale listings, about 52,000 marked “with title deed” and about 19,700 “mortgage-eligible”. Of those, up to 111,111 ₼ (fits the preferential limit with 10% down) about 1,600, up to 176,470 ₼ (the standard limit with 15% down) about 5,900. The “See mortgage-eligible apartments” button opens the section with this filter and the price ceiling you entered.
The calculator is one of the tools in the “Prices” hub; next to it are “What is my home worth?” (how it works), prices by district and the Prayk Index (introduction). Our pieces on buying versus renting, rental yields and the “Apartment investment” page give the mortgage decision its context.